
Homeowners facing a list of renovation priorities are always making tradeoff decisions.
A new kitchen is expensive and rewarding.
A bathroom remodel improves daily quality of life. New windows improve comfort and reduce heating and cooling costs.
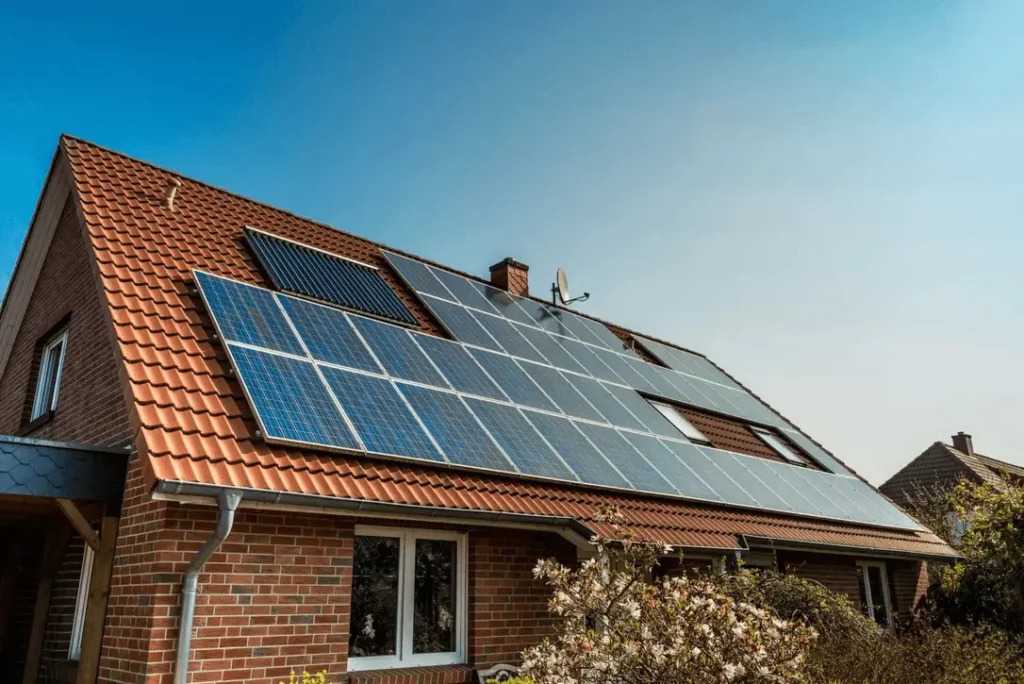
Solar installation offers a different kind of return, one that is measurable, documented, and in many cases more financially compelling than the alternatives.
The comparison is worth making explicitly.
The standard benchmark for renovation return on investment is the annual Cost vs. Value Report published by Remodeling magazine, which surveys real estate agents and contractors to estimate what percentage of renovation costs homeowners recover at sale.
The numbers vary by project type and by market, but the pattern is consistent: most interior renovations return less than 70 cents on the dollar at resale, and many return less than 60 cents.
What the Cost vs. Value Data Shows
The Remodeling Cost vs. Value Report is frequently cited in real estate conversations as evidence that most renovations do not pay back at sale.
A major kitchen remodel averages a return of around 30 to 60 percent depending on the market and the scope. A bathroom addition returns in a similar range.
These are not poor investments in the sense that they improve quality of life and make the home more competitive in its price range, but they are not financial return generators in the way that solar, with its ongoing utility savings and documented sale premium, can be.
The difference is that solar produces financial return in multiple ways simultaneously. The monthly utility savings are real and begin immediately.
The federal tax credit reduces the net cost of the investment by 30 percent in the year of installation. And the Lawrence Berkeley National Laboratory research, cited consistently by real estate professionals and appraisers, documents a sale premium for owned solar systems that is distinct from the operational savings.
The Seven-Year Threshold
The financial case for solar is strongest for homeowners who plan to remain in the property for seven or more years.
The payback period for a residential system, after the federal tax credit, typically falls in the range of six to ten years depending on the market’s electricity rates, the system size, and the financing structure.
Homeowners who are past their payback point are essentially generating free electricity, and each additional year of ownership adds to the total financial return.
Homeowners who plan to sell within three to five years face a more nuanced calculation.
The sale premium documented in the research is real but represents a partial recovery of the installation cost rather than a full return.
The federal tax credit helps significantly, reducing the effective investment by 30 percent, but the full financial case for solar is built on the combination of tax credit, operational savings, and sale premium, all of which require time to accumulate.
For short-horizon owners, reviewing home improvement ROI guidance before committing to solar is worthwhile.
Financing Structure and Its Effect on Returns
The way a solar installation is financed has a significant effect on the financial return.
Cash purchases maximize the financial return but require upfront capital.
Solar loans allow homeowners to begin capturing savings immediately while spreading the cost over time, though interest charges reduce the net return.
Leases and power purchase agreements allow homeowners to access solar savings with no upfront cost but typically do not generate a sale premium, because the buyer acquires a contract rather than an asset.
Andrew Hoesly runs SolarTech and works with homeowners navigating the solar investment decision against competing renovation priorities.
“The honest comparison isn’t solar versus a kitchen remodel,” Hoesly said. “It’s solar versus a kitchen remodel versus doing nothing, and ‘doing nothing’ still has a cost if your utility bills keep rising.
When you run the full numbers, solar’s return profile tends to hold up well against almost anything else a homeowner could spend that money on.”
The most useful way to compare solar against other renovation options is to build a simple financial model that accounts for the net installation cost after the federal tax credit, the estimated monthly savings based on the local utility rate and the system’s projected production, the expected payback period, and the documented sale premium for the market.
That model will produce different outputs in different markets, but in most cases, it will show that solar compares favorably to kitchen and bathroom renovations when evaluated on financial return over a seven-to-ten-year horizon.
The homeowners who approach this comparison honestly, running the numbers rather than relying on intuition, tend to find that solar’s combination of tax credits, operational savings, and resale value makes it one of the more compelling options on the renovation priority list.
For more guidance on home investment decisions, visit CorbyHomes.
